If You Need Insurance Involved, We Can Handle It.
If you don't, we'll tell you that too. Most people have never filed a roof insurance claim and don't know what's normal. We're a retail roofing company first, and we work residential and commercial roofs whether insurance is involved or not.
On this page
We don't chase storms or show up after every hailstorm pushing claims. When a claim makes sense, we document the damage and coordinate with your adjuster. When it doesn't, we tell you, even though that means less work for us in the short term.
When Does a Repair Actually Need Insurance?
Not every roof problem is a claim. Insurance typically covers storm damage: hail, wind or a falling branch. Normal wear, aging materials and routine maintenance issues generally aren't covered, and filing a claim for them can hurt your policy history. Part of a good inspection is telling you which situation you're in before anyone mentions the word "claim."
When a claim covers a replacement, we install the new roof as a complete GAF system. If you’re considering a Class 4 impact-rated GAF shingle, ask your carrier whether it qualifies for a discount.
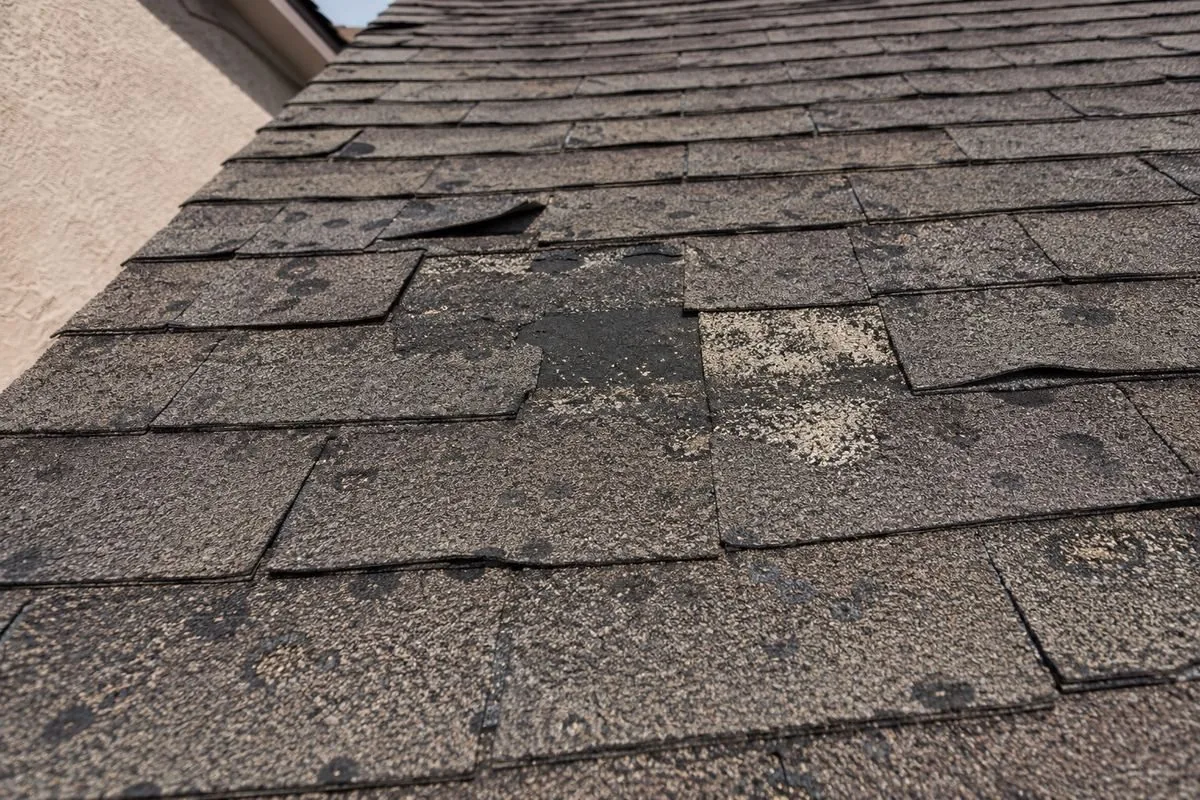
- Photo documentation of storm damage, done thoroughly
- Meeting your adjuster on-site when a claim is warranted
- Plain-language explanation of the process, no jargon
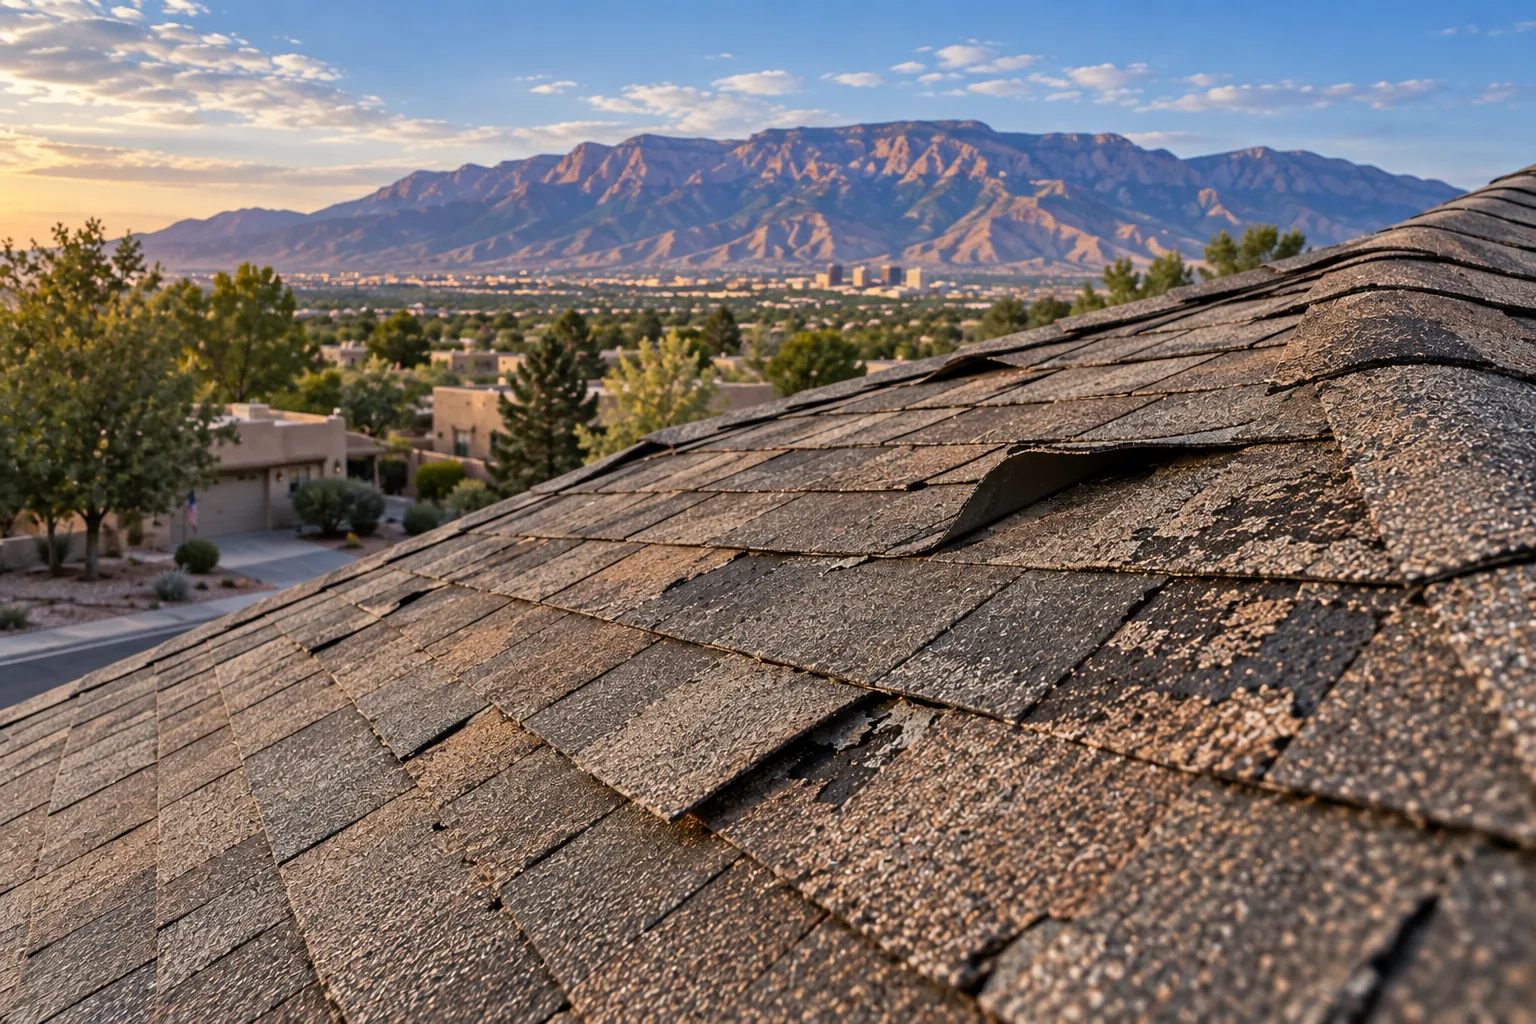
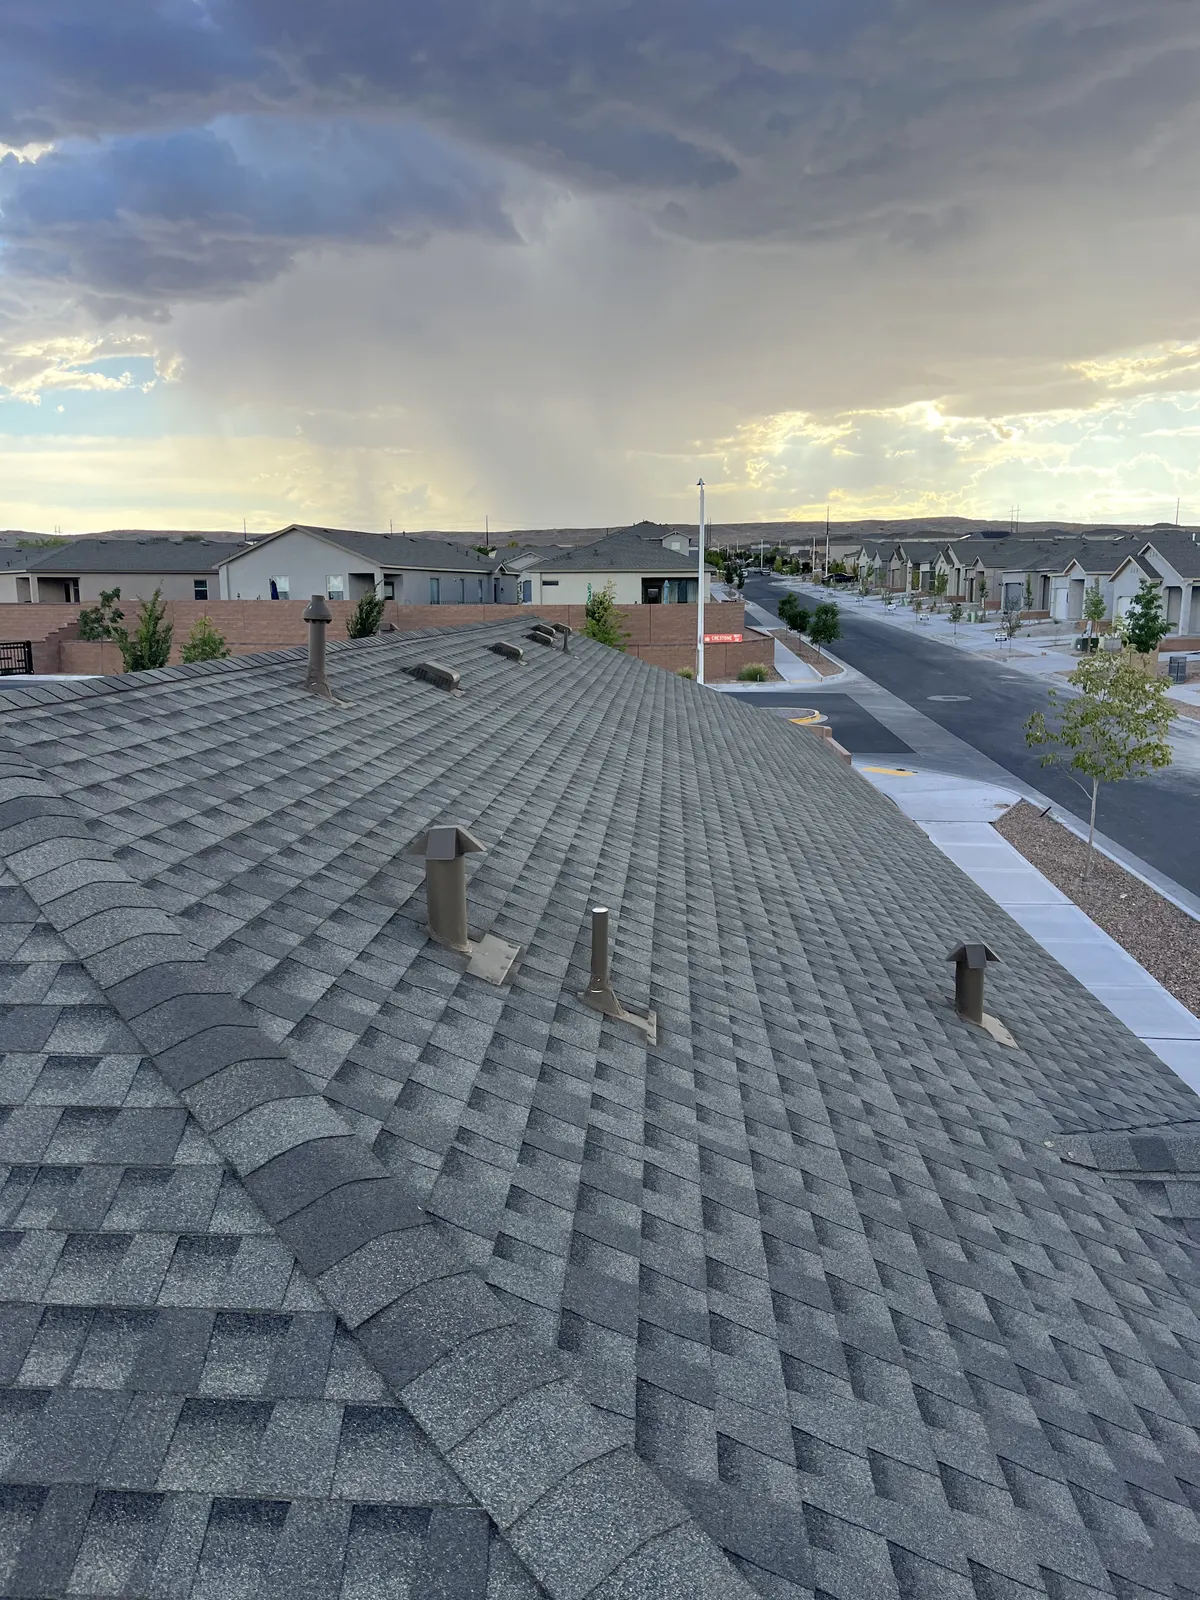
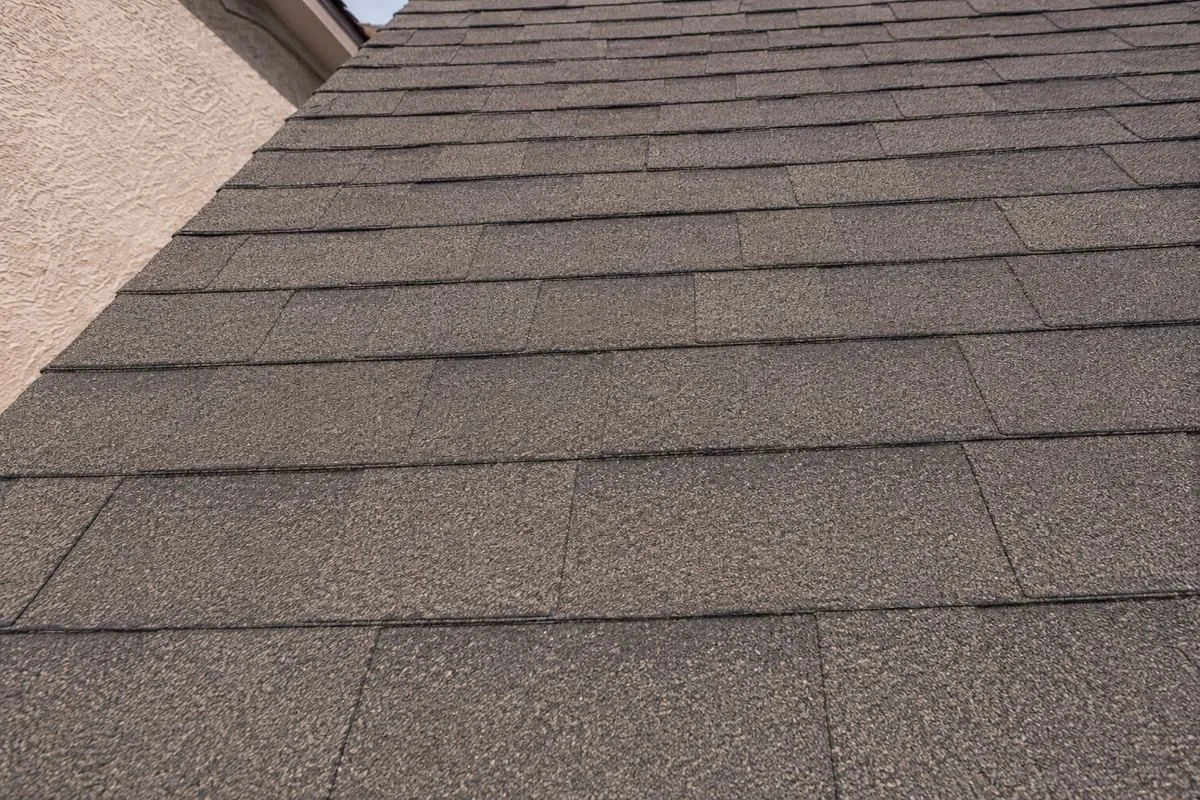
Examples of claim documentation photos
Actual Cash Value vs. Replacement Cost
Your policy pays out one of two ways, and that changes what you owe out of pocket. Most people never get this part explained clearly.
Pays what your roof is worth today
Factors in age and wear, so an older roof gets a smaller payout even if replacing it costs the same as it would for a newer one.
Pays what replacement costs
No depreciation for age. It's often paid in two parts: an initial ACV amount, then the remainder once the work is done.
Knowing which one your policy has tells you what to expect to pay. Check it before you're in the middle of a claim.
Retail Roofing First, Not Storm-Chasing
We do residential, commercial and new-build roofing, including partnering with other builders on individual homeowners' projects, with or without a storm involved. We're glad to help with insurance, but it isn't the reason we knock on your door.
Frequently Asked Questions
Do you inflate claims to get more work?
No. We document the damage that's there. That's also what holds up with insurers. Inflated claims tend to get flagged and delay everything.
Do I need insurance involved, or can this just be a normal repair?
It depends on the cause. Storm damage typically qualifies and normal wear usually doesn't. Ask us during an inspection and we'll tell you which one you're dealing with.
What's the difference between ACV and RCV, and why does it matter?
ACV pays what your roof is worth today, factoring in age. RCV pays what replacement costs, without depreciation. It directly affects your out-of-pocket cost, so it's worth knowing before you file.
Not sure if it's worth a call?
A Free Roof Report tells you where your roof stands, with no obligation.