Roof Insurance Coverage, Explained Without the Runaround
Filing a claim shouldn't feel like a second job. This is what happens, what to document, and what to do if your insurer says no. We work these claims with New Mexico homeowners every storm season.
Insurance guides and storm resources
Local storm trackingStorm Events Near You
Recent hailstorms in our service area, mapped and verified, with what to do if your home was in the path.
For walls, see our guide to stucco damage and insurance.
See storm events Start hereFiling an Insurance Claim
What to document, when to call your insurer, and what an adjuster looks for on your roof.
Read the guide New Mexico specificFiling After a Hailstorm in NM
State-specific timing, documentation, and what New Mexico adjusters see most on storm-damaged roofs.
Read the guide Working with your insurerWorking With Insurance Adjusters
Having a contractor present during the inspection is normal practice. It isn't an adversarial move.
Read the guide If you've been told noClaim Denied or Underpaid?
Your escalation path in New Mexico: written explanations, re-inspections, appraisal, OSI complaints, and the deadline that keeps running while you negotiate.
Read the guide Policy not renewingNon-Renewal Because of Your Roof
What New Mexico requires in the notice, your options before the policy ends, tile roofs flagged as too old, and how to prove your roof's age.
Read the guide What you'll get paidACV vs. RCV Explained
Actual cash value, replacement cost value, recoverable depreciation, and deductibles. These terms decide what your check looks like.
Read the guide Know your rightsNew Mexico Consumer Protections
What state law requires of your insurer under NMSA § 59A-16-20, plus how to verify any contractor's license before you sign.
Read the guide How claims workHow NM Insurance Handles Roof Claims
How a typical homeowners policy treats roof damage in New Mexico, from coverage and depreciation to the steps of a claim.
Read the guide Before you fileWill a Roof Claim Raise My Rates?
What can affect your premium after a roof claim, and the questions worth asking your agent before you file.
Read the guide Paying your shareFinancing Your Deductible
Ways to handle the deductible portion of a roof project, and what to watch out for.
Read the guideNot Sure If You Even Have a Claim?
Most insurance questions start the same way, with a close look at the roof. Our Free Roof Report tells you plainly whether the damage is storm-related and claim-worthy, or normal wear that insurance won't cover, before anyone files anything.
What Homeowners Insurance May Pay For
Every policy is different, and your policy language decides what's covered. In general, most homeowners policies are written to cover sudden, accidental damage, not the slow wear every roof goes through.
- Often covered: damage from a specific event, such as hail, wind that lifts or tears off shingles, or a tree limb falling on the roof.
- Usually not covered: normal wear and tear, age, lack of maintenance, and damage from a slow leak that went unrepaired.
- How the payout is figured: a replacement cost policy pays to replace damaged materials with new ones, while an actual cash value policy subtracts depreciation for the roof's age. Some policies treat roofs differently from the rest of the house, so check yours.
- Your deductible: you pay it first. Some policies have a separate wind or hail deductible, which can be a percentage of the home's insured value.
- Building code upgrades: if a repair has to meet current code, that extra cost may only be paid when the policy includes ordinance or law coverage.
Your insurer and your policy have the final word on coverage. If the damage looks like a claim, our roof insurance claim help page explains how a claim usually goes and what Timberwolf does along the way.
Your Rights Under New Mexico Law
New Mexico's Unfair Claims Practices law (NMSA 59A-16-20) sets the ground rules for how insurers must treat you after roof damage. It does not set a fixed day count for ordinary claims, but it does make it illegal for an insurer to:
- fail to acknowledge and act reasonably promptly on your claim communications
- fail to affirm or deny coverage within a reasonable time after you submit proof of loss
- fail to try in good faith to settle promptly once liability is reasonably clear
- treat an inquiry as a claim when the damage isn't covered, no payment is made and no deceptive practices are involved (added in 2025)
When the Superintendent of Insurance declares a catastrophe, such as a major hailstorm, catastrophic claims tied to it generally must be settled within 90 days, with limited exceptions such as suspected fraud or missing documentation (13.7.4 NMAC). More detail is in New Mexico consumer protections.
What Timberwolf Does on a Claim
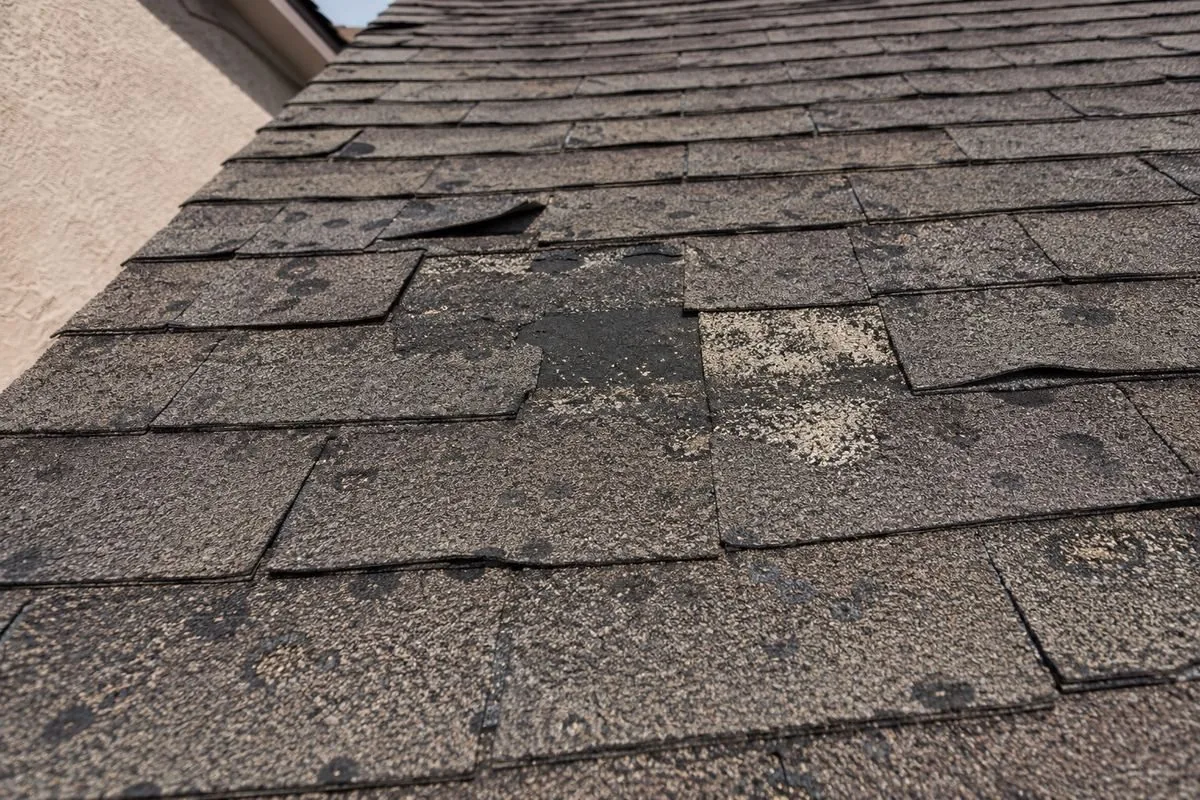
- Inspect and document. Dated photos of every damaged area, plus a written roof report you can share with your insurer.
- Separate storm damage from wear. If it's age or wear, we tell you before you file, so you don't open a claim that gets denied.
- Meet the adjuster on request. We walk the roof with them and point out what we documented.
- Build to code. Permit, decking inspection and final inspection, with the full scope on paper so the insurer sees what the job requires.
We don't act as your public adjuster or negotiate your settlement. That's between you and your insurer. What we give you is the evidence. See working with insurance adjusters and ACV vs. RCV.
When a claim covers replacement, we install the new roof as a complete GAF system as a GAF Certified contractor.
Insurance Questions We Hear Most
Does asking my insurer a question count as a claim in New Mexico?
Not when certain conditions are met. A 2025 amendment to New Mexico law (NMSA § 59A-16-20(P)), explained in Office of Superintendent of Insurance Bulletin 2025-010, bars property insurers from treating an inquiry as a claim when the damage isn't covered by the policy, no insurance payment is made, and no deceptive practices are involved. It doesn't mean every inquiry or claim is exempt from underwriting considerations, so ask your agent how it applies to you.
How long does my insurer have to handle a roof claim in New Mexico?
State law does not set a fixed number of days for ordinary claims. It requires insurers to acknowledge and act reasonably promptly, and to affirm or deny coverage within a reasonable time after proof of loss. After the Superintendent declares a catastrophe, catastrophic claims generally must be settled within 90 days, with limited exceptions.
Who do I call if my insurer is stalling?
The New Mexico Office of Superintendent of Insurance takes consumer complaints at 855-427-5674 (855-4ASK-OSI). Its Albuquerque office is at 6200 Uptown Blvd NE, Suite 400.
Stuck with an insurer? Call the Office of Superintendent of Insurance at 855-427-5674, or see claim denied or underpaid.
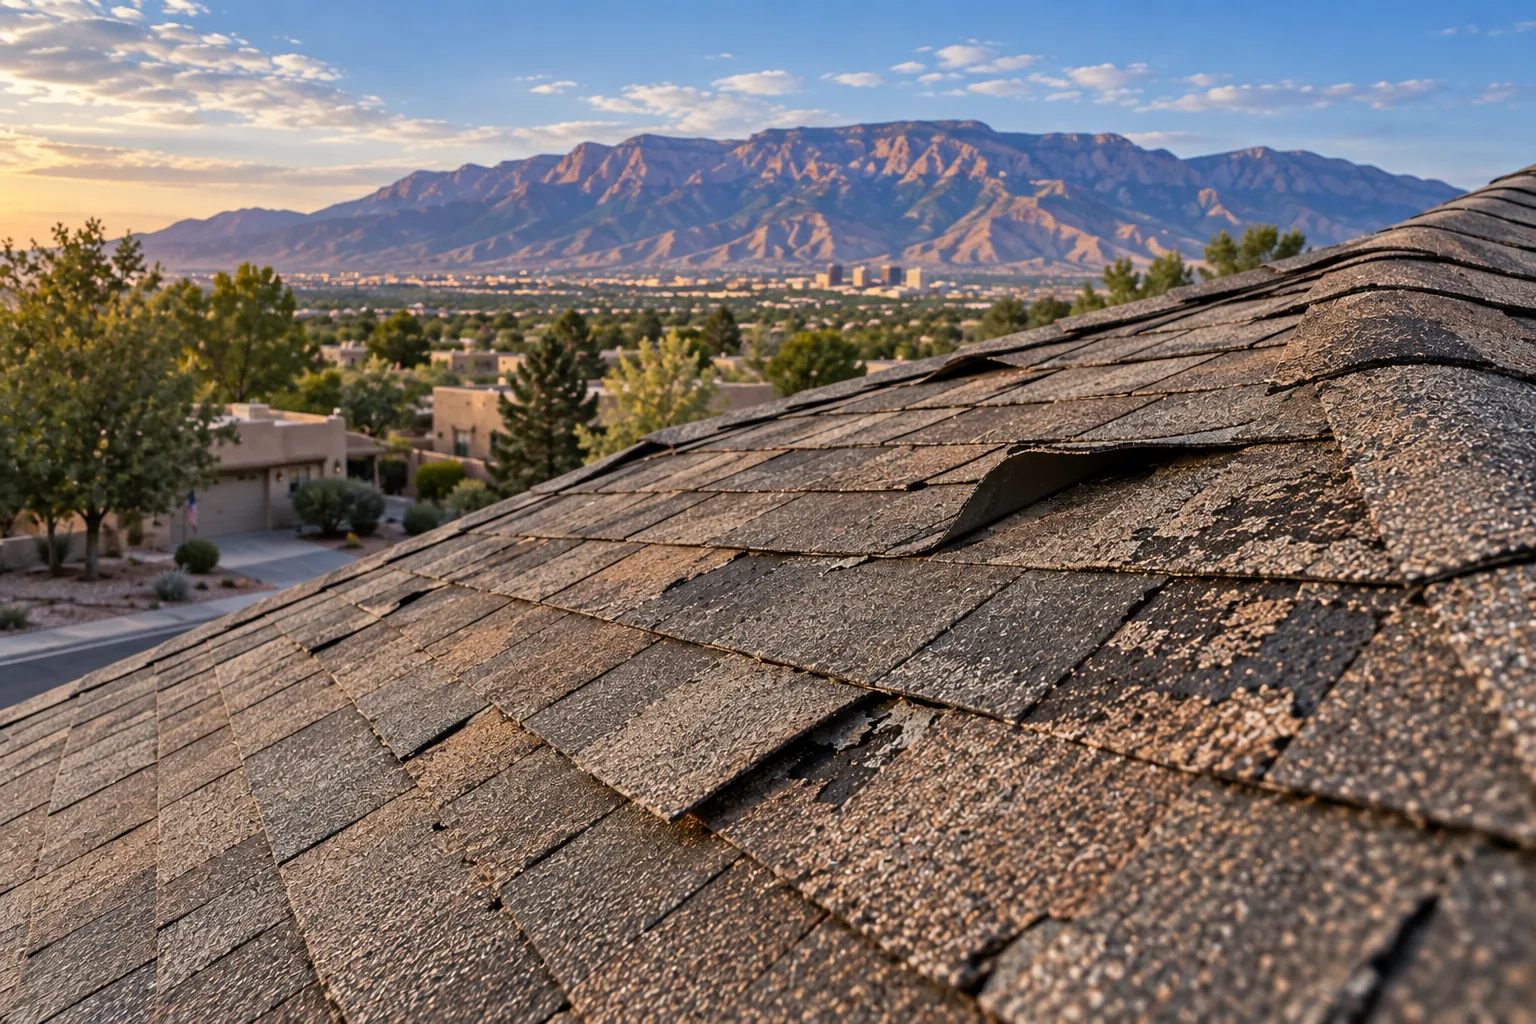
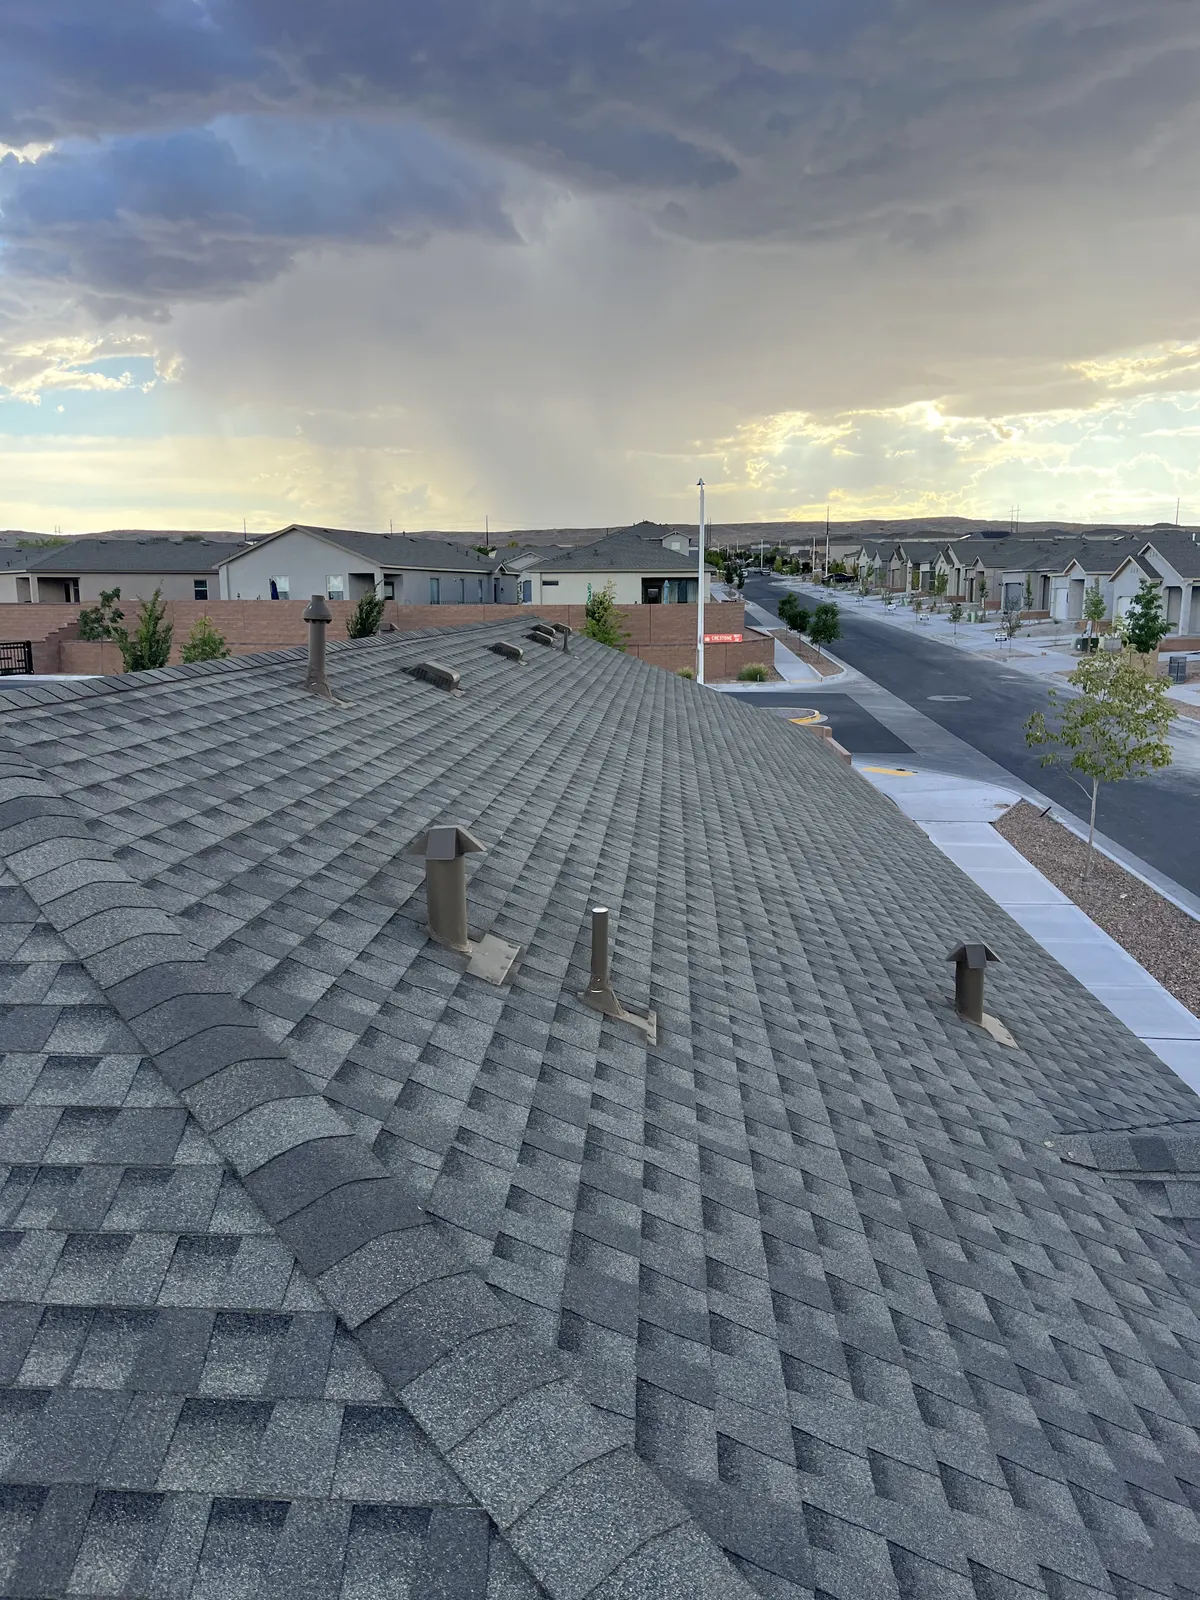
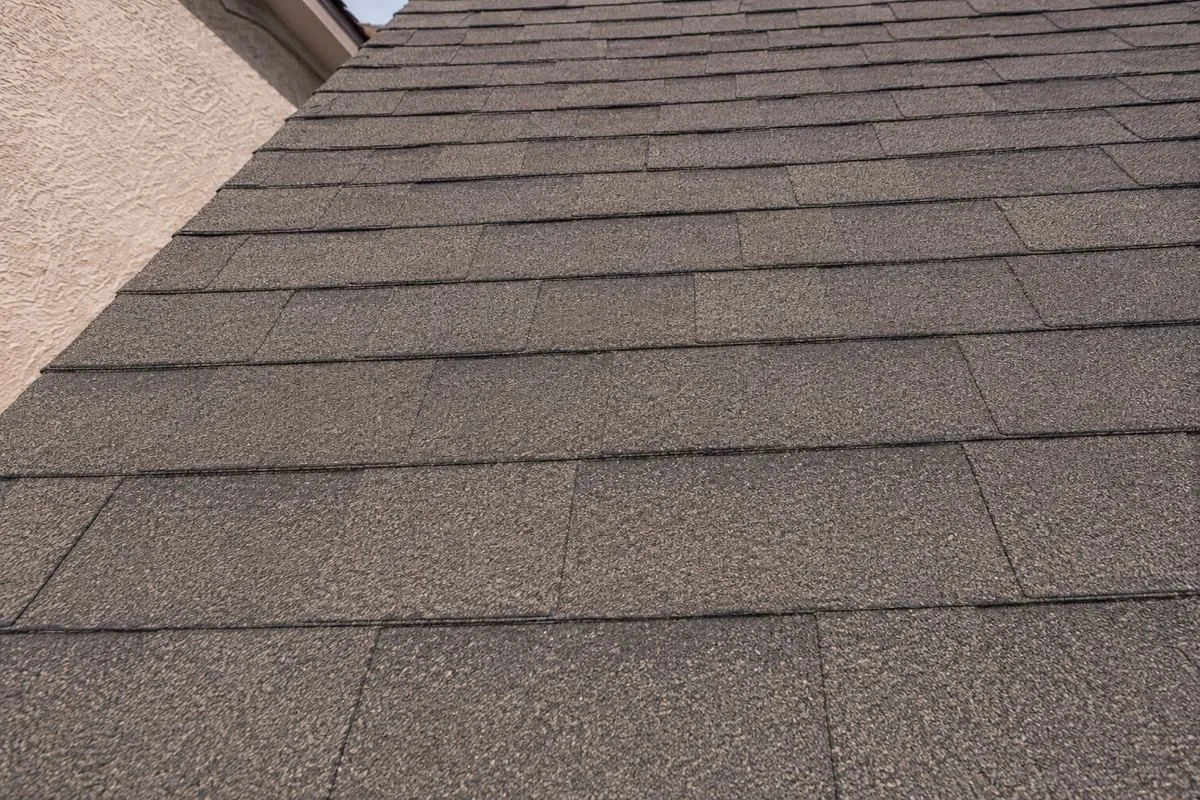
Examples of damage documentation
Think you have storm damage?
A Free Roof Report gives you a documented answer, with no obligation.