This is the single most consequential line in a homeowners policy, and most people never read it. It won't decide whether you're covered. It decides how much you receive, and on a roof the difference is rarely small.
The Two Loss Settlement Methods
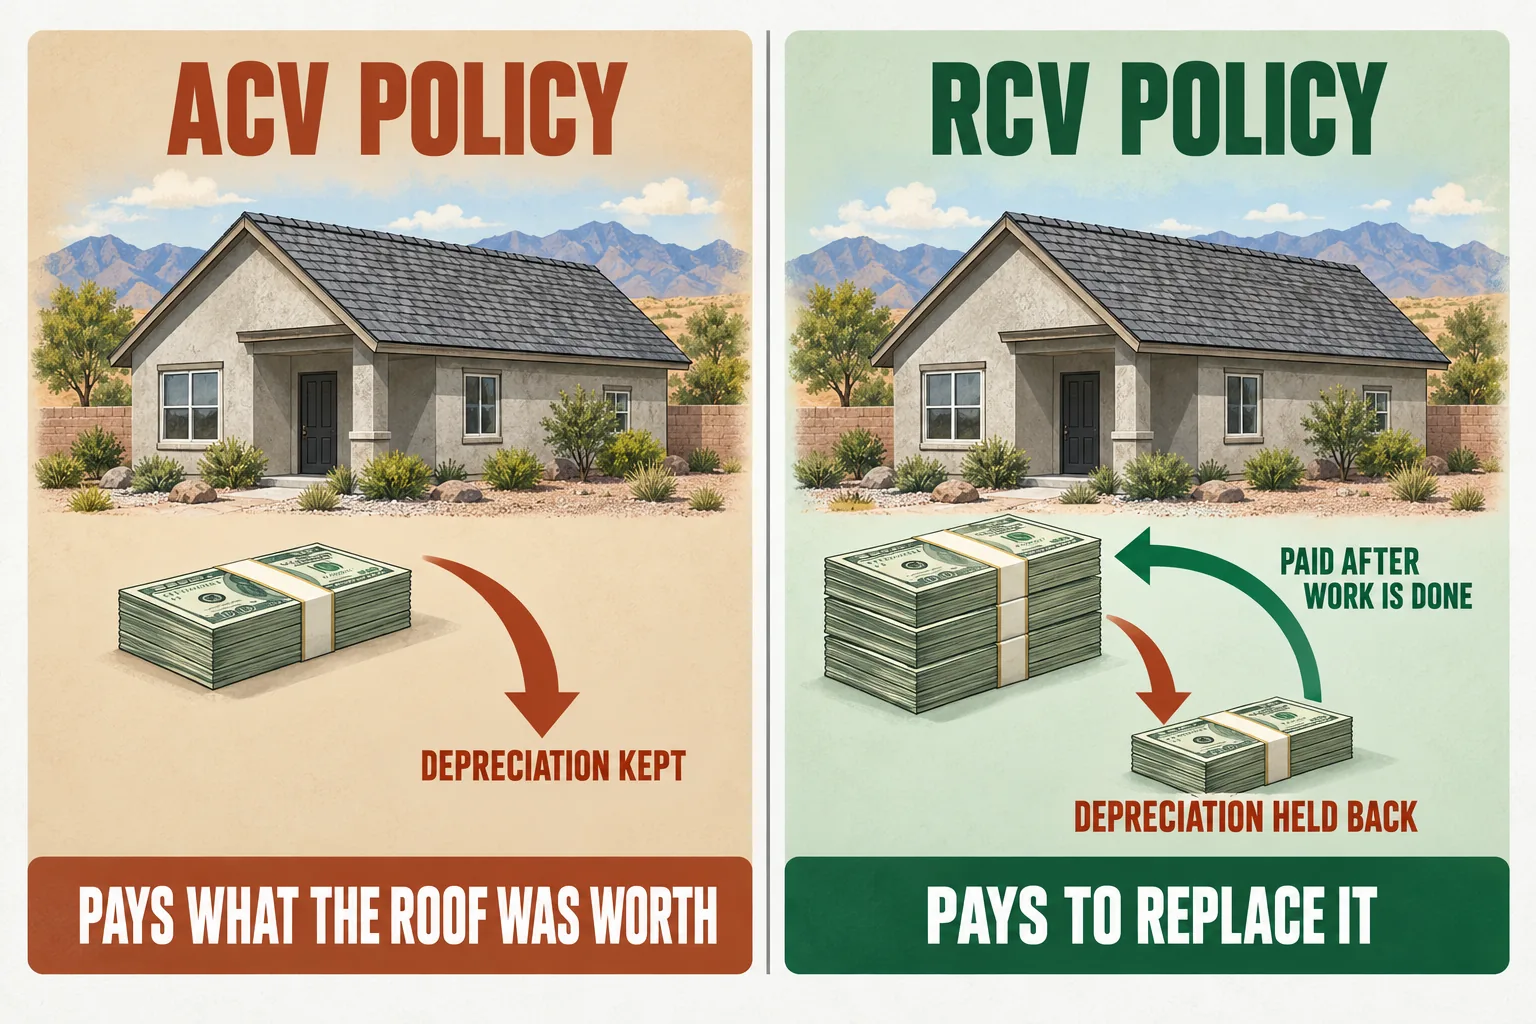
Every property policy settles claims one of two ways. The National Association of Insurance Commissioners, the standards body for state insurance regulators, defines them this way:
Actual Cash Value (ACV)
Replacement cost minus depreciation. The insurer estimates how much useful life your roof had already used up and subtracts that. You never receive that portion.
Replacement Cost Value (RCV)
The cost to repair or replace with materials of like kind and quality, with no permanent deduction for depreciation, up to your policy limits.
What Depreciation Actually Means Here
Depreciation isn't a penalty, and it isn't arbitrary. It's the insurer's estimate of how much of your roof's service life was already spent before the storm hit. A 20-year-old asphalt shingle roof rated for 25 years has, on paper, used up most of its value, so the depreciation figure is large.
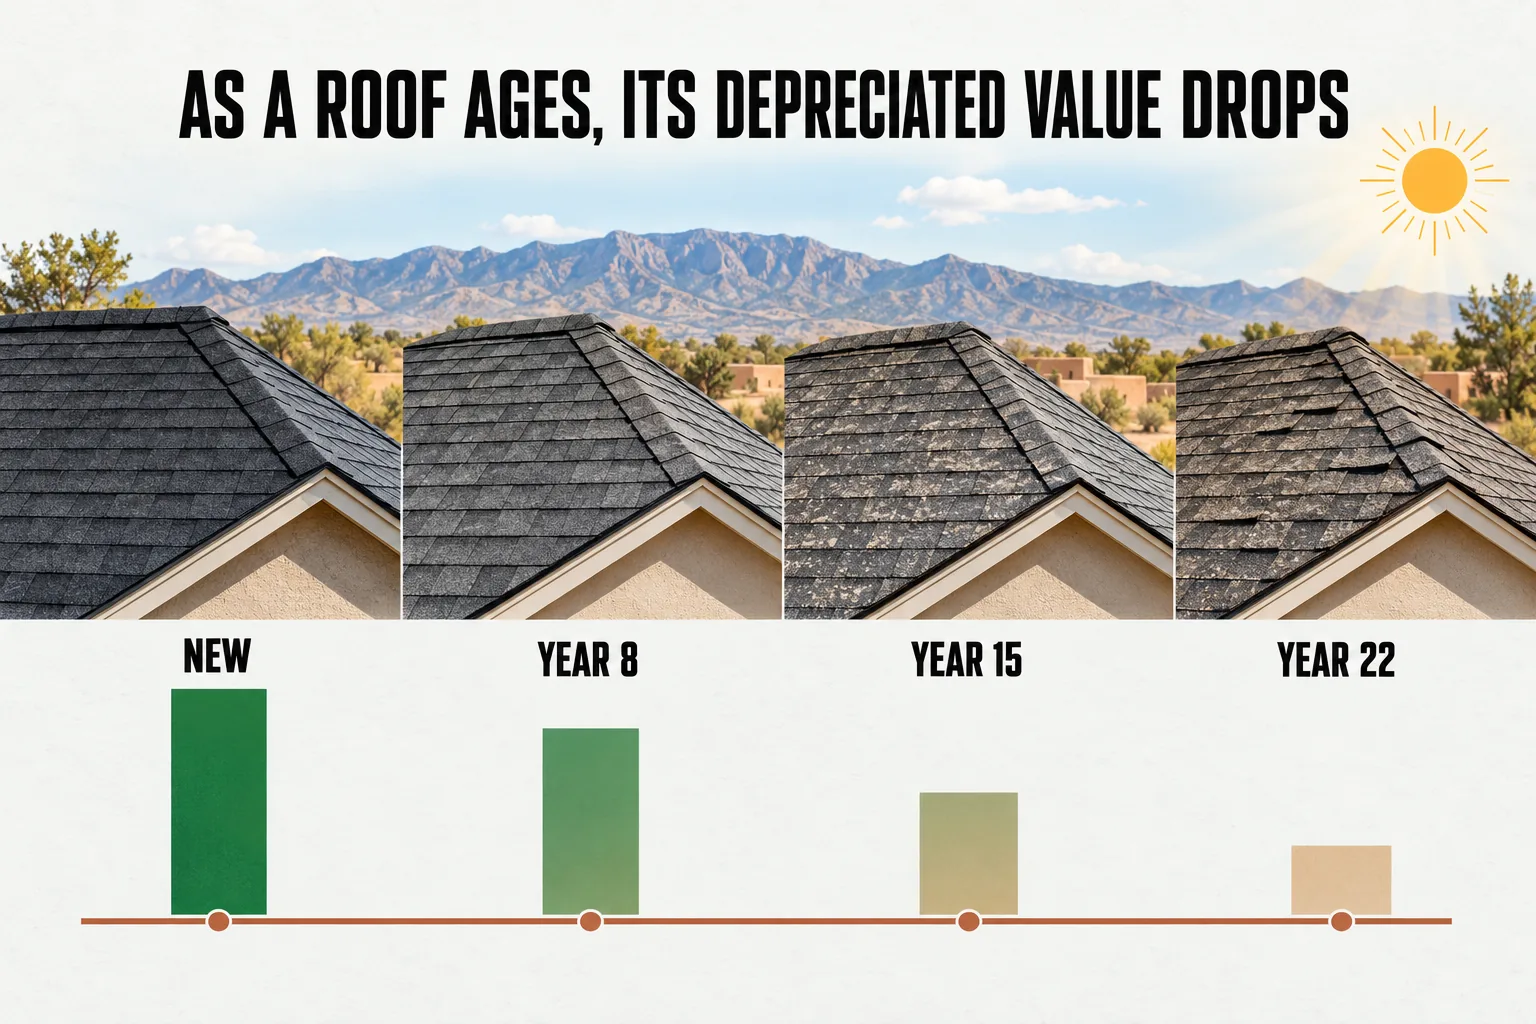
This is where Albuquerque homeowners get caught off guard. As we cover in our roof lifespan guide, altitude and UV exposure age roofs here faster than the national averages those depreciation schedules are often built on. A roof that is functionally worn out at 18 years may still be depreciated as though it were performing normally.
How Recoverable Depreciation Works
The part that confuses people most is that even on a replacement cost policy, your first check is usually an ACV check. Insurers commonly pay the depreciated amount up front, then release the withheld portion, called recoverable depreciation, after the work is finished and documented.
That two-step flow is standard practice and isn't a red flag. It does come with a hard requirement: you generally have to complete the repairs, incur the expense and submit the invoices. If you take the first check and never do the work, you typically forfeit the rest.
A worked example
Illustrative figures only. Your policy's numbers will differ, but the structure works the same way. On this claim, the settlement method is worth $6,000.
$15,549.33
$1,000.00
$16,549.33
The Roof-Specific Trap: Scheduled Roof Endorsements
A policy can be replacement cost for the house and still be actual cash value for the roof specifically. Insurers in hail-prone regions increasingly attach a roof surfaces endorsement (sometimes called a roof payment schedule or ACV roof endorsement) that switches the roof to depreciated settlement once it passes a certain age.
This means "I have replacement cost coverage" is not a complete answer. The relevant question is whether replacement cost applies to the roof, and whether an age-based schedule reduces it over time. It's worth confirming with your agent before storm season, not after.
Why we bring this up before the work, not after
Knowing your settlement method changes what a claim is actually worth to you, and sometimes changes whether filing makes sense at all. If your depreciation plus deductible comes close to the cost of the repair, a claim may not be in your interest. We'd rather tell you that during a Free Roof Report than after you've filed.
How to Find Your Own Answer in Five Minutes
- Pull up your declarations page, the summary page at the front of your policy packet.
- Find the loss settlement provision for Coverage A (Dwelling).
- Read whether it says replacement cost or actual cash value.
- Then look for a roof surfaces endorsement or roof payment schedule. It can override the above.
- Note your deductible, and whether it's a flat dollar amount or a percentage of your dwelling coverage. Percentage deductibles on wind and hail are common and are often much larger than people expect.
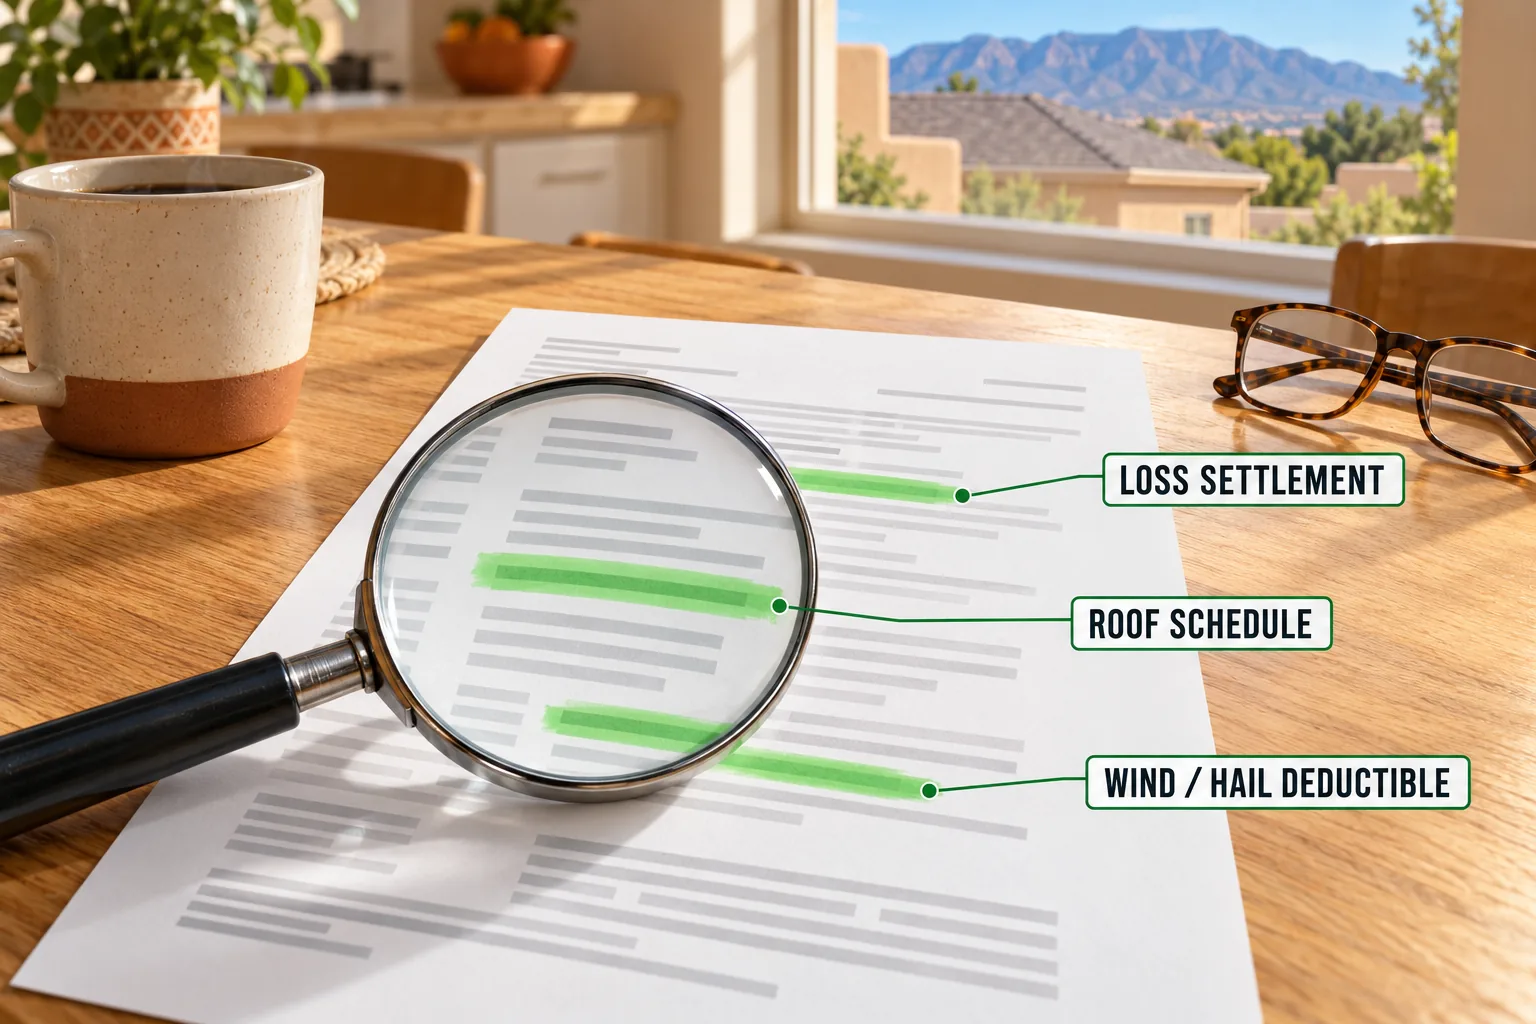
If the language isn't clear, your agent is obligated to explain it. If you don't get a clear answer, the New Mexico Office of Superintendent of Insurance operates a consumer assistance line for exactly this kind of question.